Explainable AI in Finance: 2026 Guide
Explainable AI in finance: a 2026 guide to regulation, model risk, black-box decisions, governance controls, and enterprise deployment.

Updated November 4, 2026 with SR 26-2, the EU AI Omnibus dates, new MAS and FSB guidance, a techniques comparison and an implementation checklist.
Explainable AI in finance has moved from an academic preference to an operating requirement. Banks, insurers, lenders, asset managers and fintech companies are putting machine-learning models into credit decisions, fraud detection, trading, compliance and customer service, while regulators, auditors and customers increasingly expect institutions to show how consequential outputs were produced.
| Quick answer: Explainable AI in finance means being able to show why a model produced a credit, fraud, AML, trading or pricing decision, in terms a customer, validator or supervisor can check. It combines interpretable models or tools such as SHAP and counterfactuals with documentation, validation, monitoring and human oversight, as model risk and consumer-credit rules require. |
This guide explains what financial institutions need from explainability, where black-box models create the most risk, which rules apply in each region, how the main techniques compare, and how to build a practical control system without abandoning high-performing AI.
The Pulse
AI adoption is no longer the experimental part of the story. Governance is. A joint Bank of England and Financial Conduct Authority survey found that 75% of responding financial firms were already using AI and another 10% planned to use it within three years. Among firms using AI, 81% employed some form of explainability method.
But adoption and understanding are not the same thing. In the same survey, 46% of firms reported only a partial understanding of the AI technologies they used, compared with 34% reporting complete understanding. One-third of AI use cases were supplied by third parties, making the explanation chain harder to own.
| 2026 signal | Reported figure | Why it matters |
|---|---|---|
| Financial firms already using AI | 75% | Explainability must operate at portfolio scale, not as a pilot control |
| Firms using an explainability method | 81% | The question is shifting from whether to explain to whether explanations are reliable |
| Firms with only partial AI understanding | 46% | Boards may be accountable for systems they cannot fully interrogate |
| AI use cases supplied by third parties | 33% | Vendor opacity becomes institutional model risk |
| Use cases with some automated decision-making | 55% | More outputs can directly affect customers, markets and operations |
| Fully autonomous use cases | 2% | Human oversight remains the dominant control model |
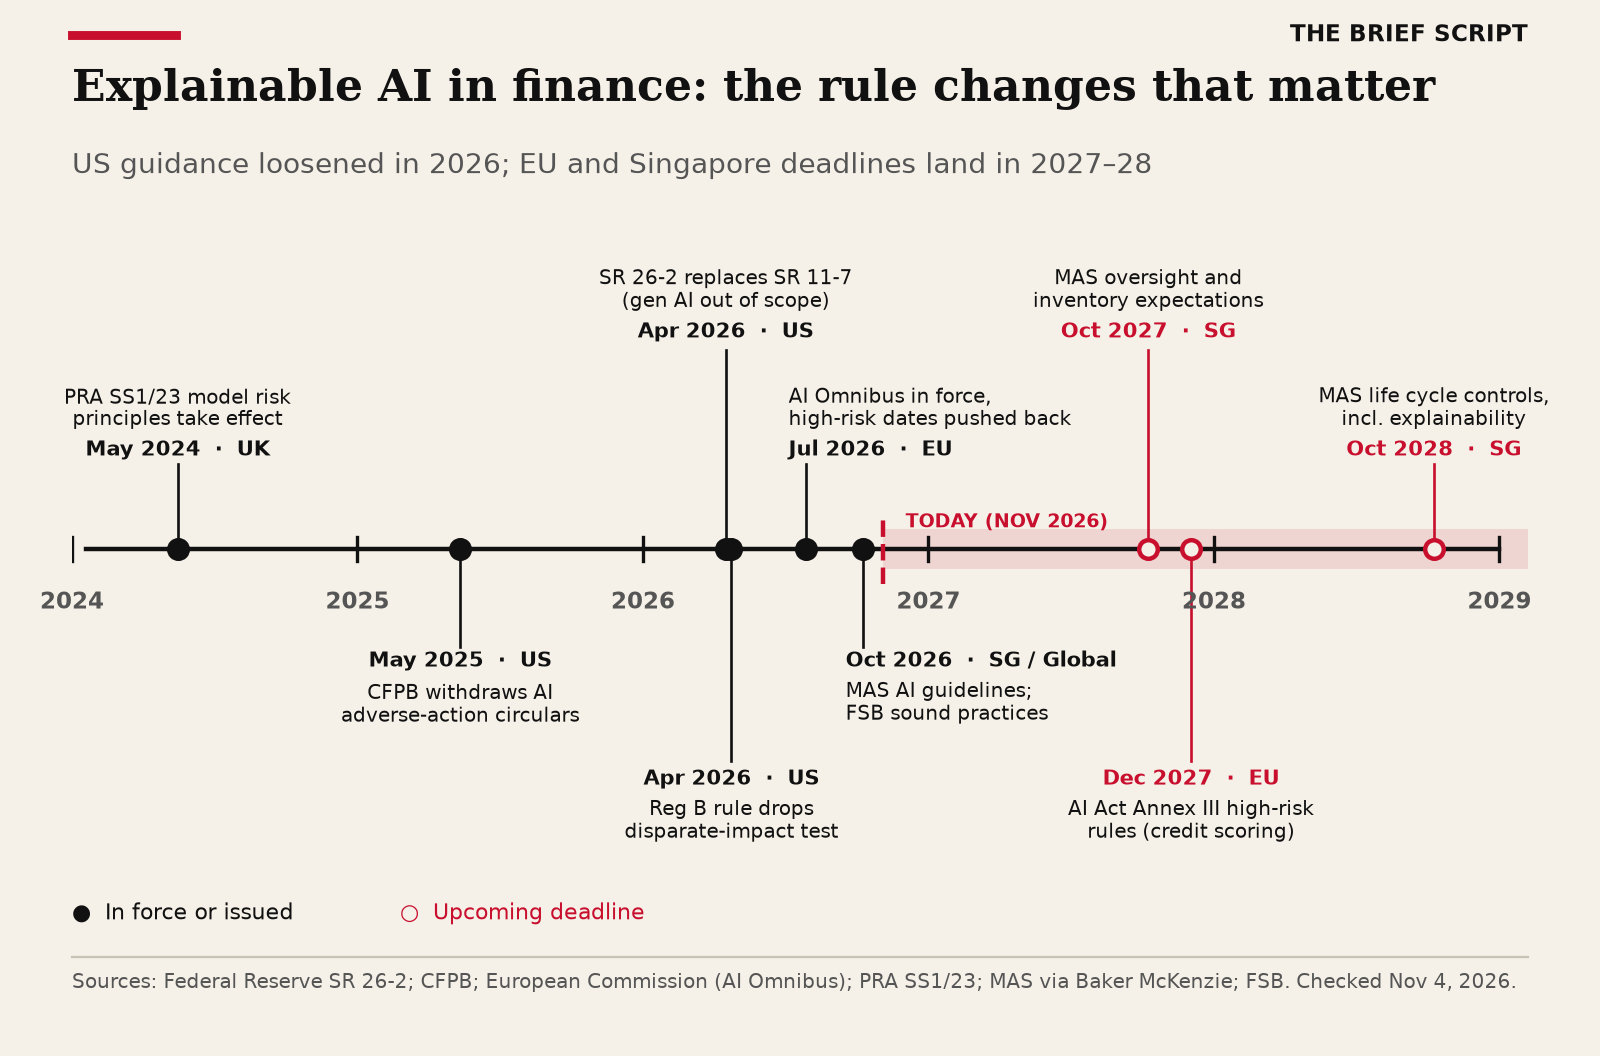
The rules moved in two directions in 2026. US bank supervisors replaced SR 11-7 with lighter, non-enforceable guidance (SR 26-2) that leaves generative AI out of scope. Elsewhere expectations got sharper: EU rules for AI credit scoring apply from December 2, 2027, Singapore issued AI risk management guidelines, and the Financial Stability Board warned banks not to over-rely on post-hoc explanation tools.
Core Significance: Explainability Is a Control System
In finance, an explanation is useful only if it helps a specific person make a specific decision. A data scientist may need feature behavior and stability tests. A model validator needs reproducible evidence. A credit applicant needs the actual principal reasons for an adverse action. A director needs to know the model’s limits, exposure and escalation path. A regulator needs records showing that the institution can govern the system throughout its lifecycle.
That is why a colorful feature-importance chart is not a complete explainability program. The institution needs a traceable chain from business purpose to data, model version, output, human action, customer communication and post-deployment monitoring. The UK FCA flagged the same gap in October 2026: firms giving consumers technical information without explaining what it meant for them.
Explainability vs. Interpretability
Interpretability describes how readily a person can understand a model’s operation or output in context. A short decision tree or a constrained scorecard may be interpretable by design. Explainability is broader: it represents the mechanisms underlying an AI system’s operation and gives stakeholders meaningful reasons for its outputs.
NIST’s AI Risk Management Framework treats explainability and interpretability as characteristics of trustworthy AI alongside validity, reliability, accountability, transparency, privacy and fairness. Its four core functions (Govern, Map, Measure and Manage) offer a useful operating model for financial institutions.
Explainable AI Techniques Compared: SHAP, LIME, Counterfactuals and Interpretable Models
XAI in finance relies on a small set of methods. Each answers a different question; none is a compliance answer on its own.
| Technique | What it answers | Best fit in finance | Main weakness |
|---|---|---|---|
| SHAP | How much each input moved this score | Credit reason codes, fraud alerts | Misleads with correlated inputs |
| LIME | Which inputs matter near one decision | Single-case diagnostics | Unstable between runs |
| Counterfactuals | What would change the outcome | Customer-facing reasons | Must avoid unrealistic changes |
| Interpretable models (scorecards, EBMs) | The model shows each input’s effect | High-impact credit and pricing | Some accuracy trade-off |
| Surrogate trees, PDPs | How the model behaves overall | Validator and board packs | An approximation |
| LLM chain of thought | The model’s own account | Drafting with human review | Not reliably faithful |
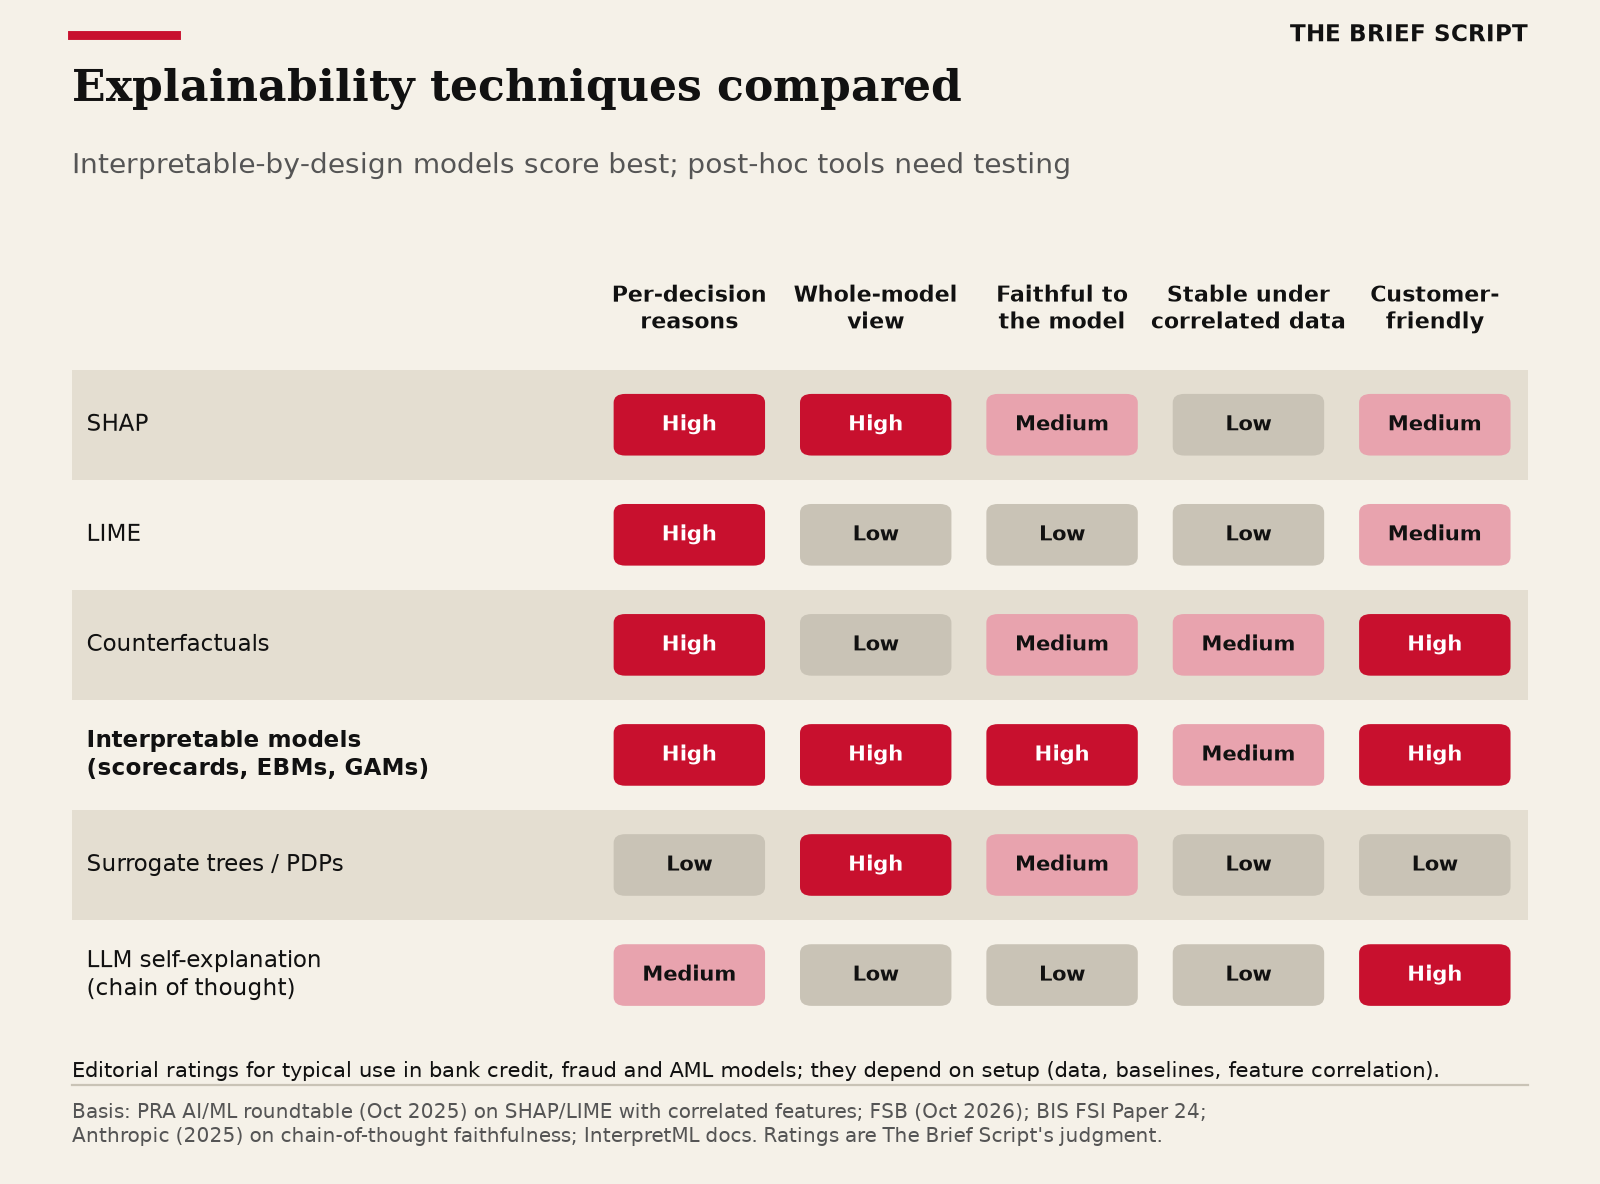
The key recent finding came from the PRA. At an October 2025 roundtable, it said SHAP, LIME and partial dependence plots assume independent inputs, which “rarely holds” in banking data, so feature rankings can be “likely to mislead”. It added that simpler techniques may be the better choice where machine learning adds little. Interpretable models have also closed much of the gap: InterpretML describes its Explainable Boosting Machine as often as accurate as state-of-the-art blackbox models.
Where Explainable AI Matters Most in Finance
| Use case | Primary explanation audience | What must be explainable | Failure risk |
|---|---|---|---|
| Credit underwriting and limits | Applicant, compliance, regulator | Specific factors that materially drove the action | Unlawful discrimination, defective adverse-action notices |
| Fraud and AML alerts | Investigator, model validator, supervisor | Alert drivers, thresholds, data lineage and false-positive behavior | Missed crime, customer harm, unmanageable alert volumes |
| Trading and portfolio models | Risk, investment committee, client | Risk exposures, constraints, regime sensitivity and override logic | Unexpected losses, conflicts, unsuitable outcomes |
| Insurance pricing and claims | Underwriter, policyholder, regulator | Pricing or claim factors and protected-class proxies | Unfair treatment, conduct and reputational risk |
| Generative-AI assistants | Employee, customer, compliance | Sources, confidence, limitations and human-review status | Hallucinated advice, privacy leakage, misleading communications |
| Capital and model-risk decisions | Senior management, audit, prudential supervisor | Assumptions, validation evidence, limitations and performance drift | Weak governance and incorrect risk estimates |
Credit Scoring and Lending
Explainable AI credit scoring is where the rules bite hardest. US lenders must give specific reasons for denials, and the EU treats scoring individuals as high-risk. Upstart says it uses SHAP values to generate adverse action reasons. First Hawaiian Bank reported a 25% increase in approval rates on Zest AI card models (vendor-reported, not independently verified).
Fraud Detection
Fraud models decide in milliseconds, so explanations mainly serve analysts and validators. Mastercard says its Brighterion platform, behind Decision Intelligence, can provide reasons for scores. In one FCA case study, a firm tested whether vulnerability indicators were influencing fraud suspicion, then fixed the model.
Anti-Money Laundering (AML)
HSBC’s Dynamic Risk Assessment, built on Google Cloud’s AML AI, finds two to four times as much suspicious activity as its old rules with 60% fewer alerts, per HSBC and Google. Investigators still need to see why a customer scored as risky. SR 26-2 also rescinded the separate US statement on BSA/AML model risk.
Trading and Investment
In markets, explanation is giving way to output control. The FMSB’s February 2026 review says explaining complex trading models “will face practical limits”, so firms should monitor outputs behind independent pre-trade limits. IOSCO’s May 2026 toolkit asks supervisors to probe model explainability.
Insurance Underwriting and Claims
The EU AI Act also treats life and health insurance pricing as high-risk. In the US, the NAIC’s AI model bulletin had been adopted by 29 jurisdictions as of November 3, 2026, while California, Colorado, New York and Texas run their own rules.
The 2026 Regulatory Map
No single “explainable AI law” governs global finance. Institutions face overlapping consumer-protection, prudential, conduct, privacy and AI-specific requirements.
- United States—consumer credit: Regulation B still requires specific and accurate principal reasons for adverse actions. The Consumer Financial Protection Bureau said in 2022 that complex algorithms are no excuse; it withdrew that circular in May 2025, but the duty itself remains. An April 2026 rule removed the disparate-impact “effects test” from Regulation B.
- United States—bank model risk: In April 2026, the Federal Reserve, OCC and FDIC issued revised model-risk-management guidance, replacing SR 11-7 and emphasizing a risk-based approach tailored to each banking organization’s model profile, size and complexity. It targets banks with over $30 billion in assets.
- United States—securities: FINRA identifies explainability, model validation, inventories, performance benchmarks, human review and autonomous-action guardrails as important considerations for AI applications under existing supervisory obligations.
- European Union: The EU AI Act combines transparency, documentation, risk-management, human-oversight and monitoring duties. Its application timeline is phased, and the AI Omnibus moved the high-risk dates, so firms should map each use case rather than rely on a single compliance date.
- Global prudential direction: A 2025 BIS Financial Stability Institute paper warns that post-hoc explanation techniques can be inaccurate, unstable or misleading. It argues for safeguards that recognize the trade-off between model performance and explainability.
The practical conclusion is straightforward: compliance cannot be reduced to selecting an explanation tool. Institutions must show that the explanation is fit for the model, use case, audience and legal obligation. For the broader policy picture, see our analysis of the AI governance gap, our guide to AI finance regulation for banks and our country-by-country artificial intelligence regulation tracker.
Explainable AI Regulations by Region
| Region | Main rules | What they expect on explainability | Key dates |
|---|---|---|---|
| US banks | SR 26-2, OCC 2026-13 | Risk-based validation; vendor models included; gen AI excluded | Apr 17, 2026 |
| US credit | ECOA / Regulation B | Specific reasons for adverse action | CFPB circulars withdrawn May 2025 |
| EU | AI Act + Omnibus | Credit scoring high-risk; logging, oversight, right to explanation | Dec 2, 2027 |
| EU banks | EBA mapping | No major conflict with banking law | Nov 2025 |
| UK | PRA SS1/23, FCA | Explainability drives model tiering | May 17, 2024 |
| Singapore | MAS guidelines, FEAT | Explainability scaled to risk | Oct 2027 / Oct 2028 |
| Global | FSB | Don’t rely on one method | Oct 15, 2026 |
Explainable AI in Banking: What Supervisors Expect in 2026
Explainable AI in banking is now mostly a model risk question. The PRA’s SS1/23 counts a model’s interpretability and explainability toward its complexity tier, which sets how much validation it gets. The MAS guidelines cover every type of AI, including generative AI and agents, treat explainability as a complexity driver, and require independent validation for high-risk use cases. The FCA praised firms that kept auditable records of prompts, outputs, model versions so challenged outcomes could be investigated.
Model Risk Management for AI After SR 26-2
For US banks, model risk management for AI now rests on SR 26-2. It names “interpretability measures” as a practical way to assess conceptual soundness, keeps proprietary vendor models in scope, and excludes generative and agentic AI as “novel and rapidly evolving”.
That exclusion is not a free pass: banks must still govern LLM tools under their wider risk frameworks, and now have to design those controls themselves.
LLM Explainability: Why Generative AI Is Harder to Explain
Large language models break the tools banks know, and asking a model to explain itself does not fix it. Anthropic’s 2025 research found that reasoning models mentioned a hint they had actually used only 25% of the time for Claude 3.7 Sonnet and 39% for DeepSeek R1, so a chain of thought is not a faithful record of why the model answered as it did.
The FSB warns that generative AI may hallucinate or “underweight relevant information in lengthy or complex inputs”. Its sound practices suggest prompt versioning, chain-of-thought logging and unique IDs for each AI agent.
What works is evidence, not introspection: approved sources with citations, humans on consequential decisions, structured output tests and full logs. Where data cannot leave the bank, a private LLM makes logging and change control easier.
Explainable AI Tools for Financial Institutions
The table lists features each vendor documents; it is not a ranking. For the governance layer, see our comparison of AI governance tools.
| Tool | Explainability methods documented |
|---|---|
| IBM watsonx.governance | LIME, contrastive, SHAP |
| H2O Driverless AI | Shapley, k-LIME, surrogate trees, PDP |
| SAS Risk Modeling | SHAP, LIME, bias detection |
| Fiddler AI | Shapley, Integrated Gradients |
| Azure ML Responsible AI | Global and local SHAP |
| Amazon SageMaker Clarify | Kernel SHAP, PDP (closed to new customers) |
| InterpretML (open source) | EBMs, glassbox models |
The Enterprise Playbook: Eight Controls That Work
1. Start with the decision, not the algorithm
Write down what the system influences, who can be affected, the cost of a wrong output and which human or automated action follows. This determines the required level of explanation.
2. Tier models by impact
A marketing-content assistant should not face the same controls as a credit-decision model. Use tiers based on customer impact, financial materiality, autonomy, regulatory exposure, data sensitivity and reversibility.
3. Define an explanation contract
For each system, specify the audience, format, latency, level of detail and prohibited claims. A customer-facing reason code, an auditor’s evidence pack and a developer’s diagnostic plot are different products.
4. Validate the explanation—not only the prediction
Test whether explanations are faithful to the model, stable across small input changes, reproducible by an independent team and understandable to the intended audience. A plausible story is not necessarily a faithful explanation.
5. Preserve lineage
Retain the model version, data snapshot, key transformations, prompt or configuration, output, explanation, reviewer and final action. Without lineage, institutions cannot recreate past decisions or investigate complaints.
6. Put limits on autonomy
Set thresholds for mandatory review, transaction caps, confidence floors, override rights and kill switches. Human oversight should have an explicit purpose; a person who cannot understand or change the outcome is not an effective control.
7. Contract for vendor transparency
Require vendors to provide documentation, material-change notices, testing access, incident support and enough evidence to meet the institution’s obligations. “Proprietary model” should not mean “unreviewable risk.”
8. Monitor explanations after launch
Track drift, overrides, complaints, adverse-action reason distributions, subgroup outcomes, explanation stability and control breaches. Governance cost should be included in the real cost of enterprise AI deployment, not treated as an afterthought.
Explainable AI Implementation Checklist
Our AI audit checklist covers the evidence auditors will ask for.
- Inventory every AI model and vendor feature touching credit, fraud, AML, pricing or trading.
- Map each to its rules: EU Annex III, US adverse action, SS1/23, MAS.
- Tier by impact, complexity and reliance.
- Try an interpretable model first for high-impact decisions.
- Pick explanation methods per audience.
- Test explanations for faithfulness, stability and reproducibility.
- Check adverse-action reasons against model drivers.
- Run subgroup and proxy tests before launch and on a schedule.
- For LLMs, restrict sources and log prompts, outputs and versions.
- Contract for testing access, change notices and exit.
- Set monitoring thresholds, owners and a fallback.
- Keep an evidence pack per model.
Data Insights: What to Put on the Dashboard
| Metric | What it reveals | Example escalation trigger |
|---|---|---|
| Explanation stability | Whether similar inputs produce materially different reasons | Unexpected movement beyond the validated tolerance |
| Reason-code distribution | Which factors drive customer outcomes over time | Sudden concentration in one factor or subgroup |
| Human override rate | Whether reviewers trust or routinely correct the model | Sharp rise, persistent zero, or unexplained team variance |
| Subgroup performance | Potential disparate impact or uneven error rates | Material gap against the approved fairness threshold |
| Vendor/model changes | Whether the deployed system still matches the validated version | Undocumented change to data, model or safety controls |
| Complaint and appeal outcomes | Whether explanations help people identify and correct errors | Repeated successful appeals tied to the same reason |
| Explanation latency | Whether reasons arrive in time for the business or legal process | Missed notice or review deadline |
The Business Case
Explainability is often framed as a tax on model performance. That is too narrow. A model that cannot pass validation, support an adverse-action notice, survive an audit or earn frontline trust may never create business value, regardless of its benchmark score.
- Faster approvals: reusable evidence and clear ownership reduce back-and-forth between engineering, risk, legal and audit.
- Better model operations: explanation drift and override patterns can expose data problems before headline performance collapses.
- Lower remediation cost: traceable decisions make complaints, investigations and regulatory requests easier to resolve.
- Higher adoption: employees are more likely to rely on a model when they understand when it works, when it fails and when they should intervene.
- Stronger vendor leverage: explicit evidence requirements prevent institutions from discovering opacity after procurement.
Expert Nuance: More Explanation Is Not Always Better
Explanations can create false confidence. Post-hoc methods may simplify nonlinear behavior, change across runs or highlight correlation without establishing causation. Excessive technical disclosure can also confuse customers, expose security weaknesses or reveal proprietary information.
The right goal is therefore decision-useful, tested and audience-specific explanation, not maximum transparency. For high-impact use cases, firms may choose a more interpretable model, constrain a complex model, combine tools, or add independent review. The choice should be documented as a risk decision rather than hidden inside a data-science workflow.
Strategic Outlook
Through 2027, the differentiator will not be whether a financial institution can produce a feature-importance chart. It will be whether the institution can connect an AI-assisted decision to accountable ownership, reliable evidence, customer communication and continuous monitoring, across both internal and third-party systems.
The calendar is clear: EU credit scoring rules from December 2, 2027, MAS deadlines in October 2027 and 2028, and lighter US guidance with unchanged adverse-action duties.
The winners will treat explainability as infrastructure. They will maintain inventories, tier use cases, test explanations, preserve decision records and negotiate transparency before signing vendor contracts. That creates a platform for scaling AI safely instead of forcing every new model through a bespoke compliance crisis.
Frequently Asked Questions
What is explainable AI in finance?
Explainable AI in finance is the set of models, methods, records and governance controls that enables relevant people to understand why an AI system produced an output and how that output was used in a financial decision.
Why is explainable AI important for banks?
Banks must manage model risk, supervise automated systems, communicate certain decisions to customers and demonstrate compliance. Explainability supports validation, human oversight, customer notices, auditability and incident investigation.
Does U.S. law require lenders to explain AI credit decisions?
Yes. For adverse credit actions covered by ECOA and Regulation B, creditors must give applicants specific principal reasons. The CFPB said in 2022 that this applies even to complex algorithms. It withdrew that circular in May 2025, but the requirement in Regulation B itself still stands.
How do enterprises deploy AI in compliance-heavy industries?
They start with a clearly bounded use case, classify its impact, document data and model lineage, validate performance and explanations, assign accountable owners, establish human-review thresholds, monitor the system after launch and maintain evidence for audits and customer challenges.
Are SHAP and feature importance enough for AI explainability?
No. They can be useful technical tools, but an enterprise program also needs explanation testing, audience-specific communication, governance, lineage, validation, monitoring and escalation controls. The PRA has warned that SHAP and LIME can mislead when input features are correlated.
Can a financial institution use a black-box AI model?
Potentially, depending on the use case and jurisdiction. The institution must assess whether safeguards, independent validation, human oversight and post-hoc explanations reduce risk enough to meet its legal and business obligations. Some decisions may require a more interpretable alternative.
What is XAI in finance?
XAI in finance is explainable AI applied to financial services: methods such as SHAP, counterfactuals and interpretable models, plus the testing and records that let firms justify AI decisions to customers and regulators.
What is explainable AI credit scoring?
It is credit scoring where each decision traces to the factors that drove it, through an interpretable scorecard or per-applicant attributions turned into reason codes.
When does the EU AI Act apply to credit scoring?
Credit scoring of individuals is high-risk under Annex III. After the AI Omnibus, those obligations apply from December 2, 2027.
What does SR 26-2 mean for model risk management of AI?
SR 26-2 replaced SR 11-7 in April 2026 with tailored guidance for banks over $30 billion in assets. It covers non-generative AI, accepts interpretability measures in validation, and excludes generative and agentic AI.
Can large language models be explained in banking?
Only partly. Their self-explanations are not reliably faithful, so banks rely on approved sources, citations, logging, output testing and human review.
Primary Sources
- Bank of England and FCA: Artificial Intelligence in UK Financial Services
- Federal Reserve: Revised Guidance on Model Risk Management, SR 26-2
- NIST AI Risk Management Framework
- CFPB: Adverse Action Requirements for Complex Algorithms (Circular 2022-03, withdrawn May 2025)
- FINRA: AI Key Challenges and Regulatory Considerations
- European Commission: AI Act Regulatory Framework
- European Commission: AI Omnibus enters into force
- PRA: SS1/23 Model risk management principles for banks
- MAS: Supervisory expectations on responsible AI adoption
- FSB: Sound Practices for Responsible Adoption of AI, final report
- BIS FSI: Managing Explanations
- Anthropic: Reasoning models don’t always say what they think
Updated November 4, 2026 (first published July 25, 2026). This article provides general information and is not legal, investment or compliance advice.